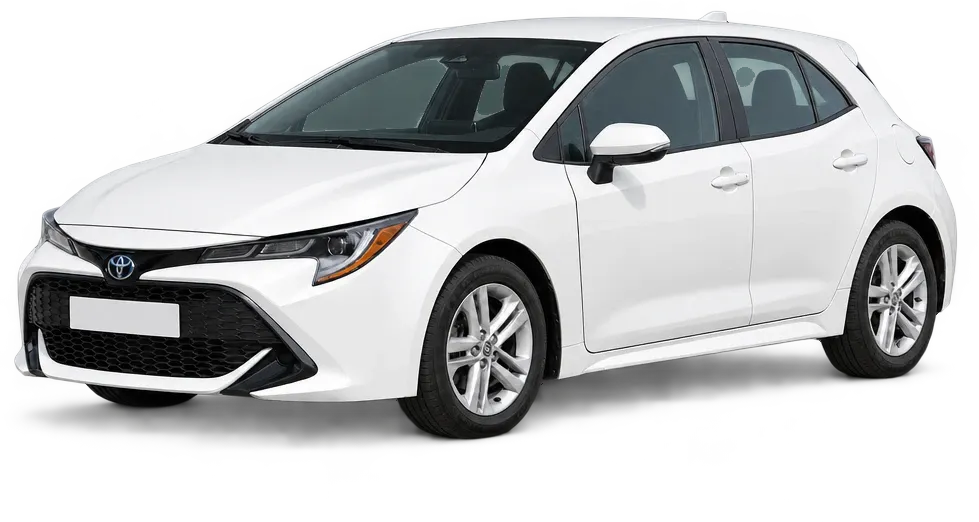
Ascent Sport
The entry grade and the most common used Corolla.
The Toyota Corolla is a reliable small car that is cheap to run, and a favourite first car. If you’ve found a used one, you can finance it from a dealer or a private seller.
Fastest approval on record 7m 28s
The short answer
You can finance a used Toyota Corolla with a secured car loan. Lenders look at the car’s age, kilometres and value, and at your income and credit history. Hatchbacks are usually low-priced, so loans tend to be smaller and easier to fit into a budget.
 See what lenders may offer you
Estimate your repayments
Loan term
Credit history
$0per week
$0 per month at an example 11% p.a.
Want your real numbers?
Answer a few quick questions and a broker will come back with options lenders may offer you.
Estimate only. Example rates are for illustration, not offers or comparison rates, and fees aren’t included.
The Corolla suits first-car buyers, commuters and anyone who wants a car that is cheap to run and easy to own. Its reliability makes it one of the safest used-car buys, and the hybrid versions are very economical in traffic.
Lenders want the Toyota Corolla to be good security for the loan. They check its age, kilometres and market value against similar cars for sale, and many set a maximum age for the car at the end of the loan term. An older car may mean a shorter loan term or fewer lenders to choose from.
They also look at you: your income, your regular expenses, your existing debts and your credit history. Responsible lending rules mean the lender has to be satisfied the repayments are affordable for you, not just that the car is worth the money.
Hatchbacks are usually low-priced, so loans tend to be smaller and easier to fit into a budget.
Simple, reliable and affordable. A popular first car with plenty available.
Sharper styling, better safety tech and a hybrid option that uses very little fuel around town.
The grades you’ll see most in listings. Higher grades cost more to buy, insure and finance.
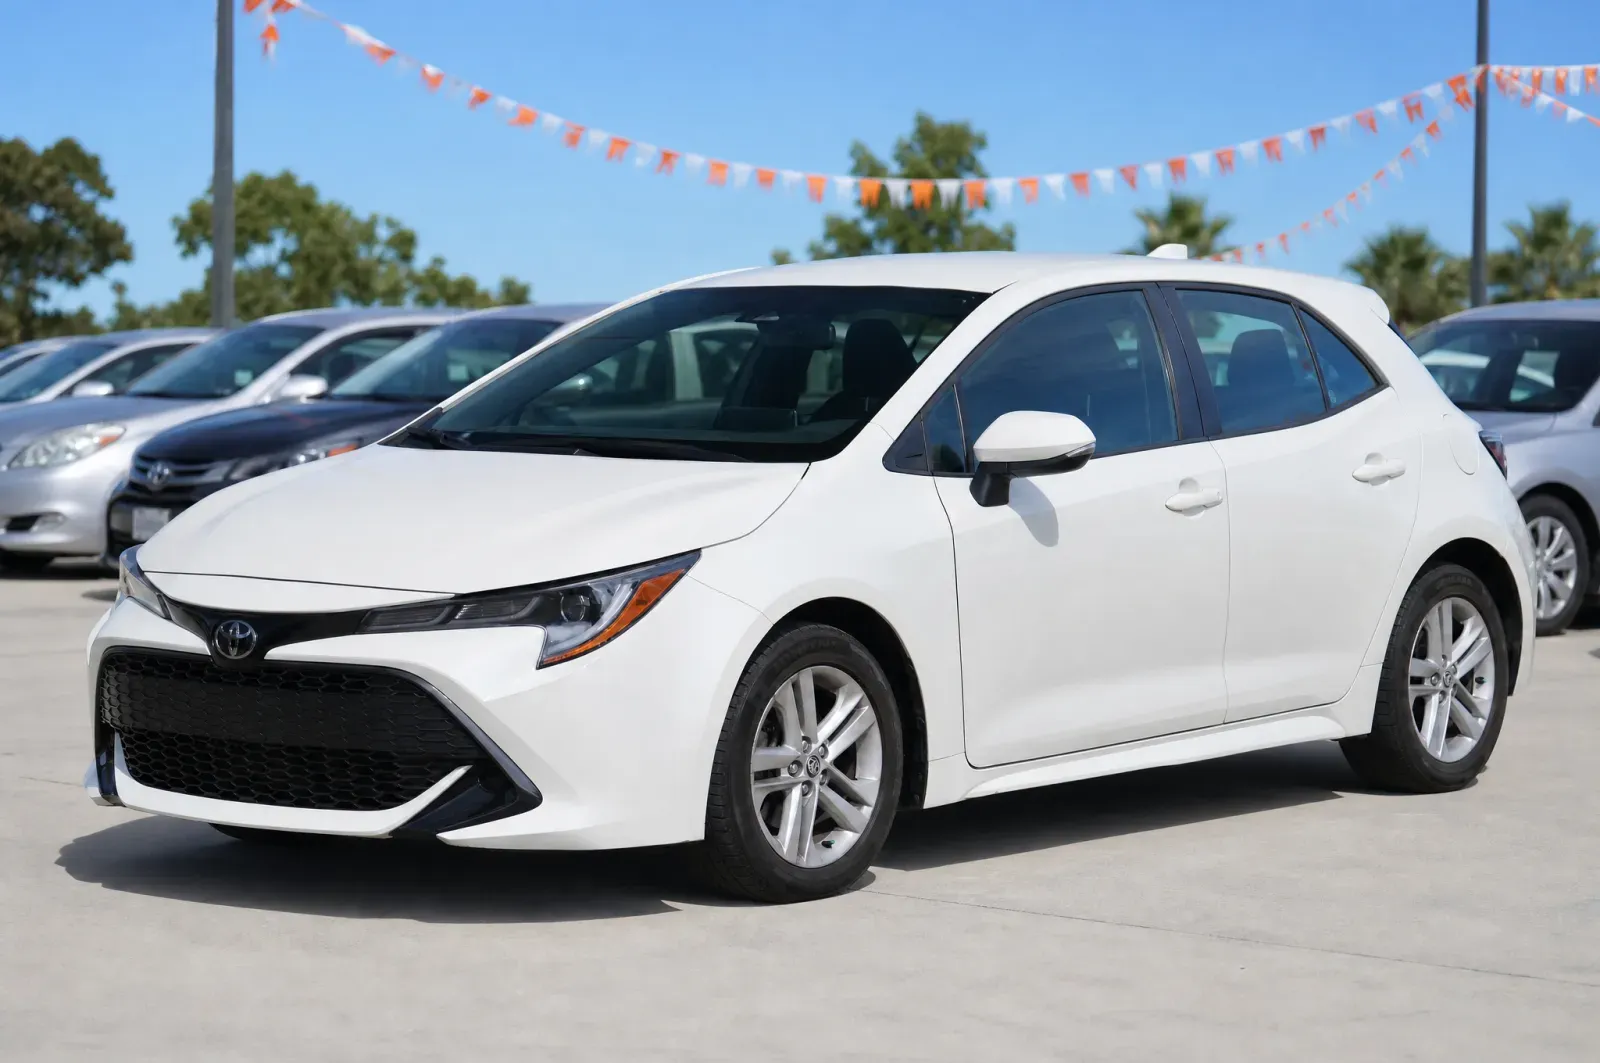
The entry grade and the most common used Corolla.
A mid grade with extra features and styling.
The top grade, with more tech and comfort.
Available across several grades, and very economical in traffic.
On hybrid versions, ask for a hybrid system health check and look for any hybrid warning lights.
Corollas are common rental and rideshare cars. Check the kilometres, seat wear and service history.
Look for parking damage, kerbed wheels and mismatched paint from minor repairs.
Check the logbook for regular oil changes and servicing at the right intervals.
Search the PPSR to confirm there is no finance owing and the car hasn’t been written off or stolen.
Get a mechanic to inspect the car before you pay, especially on a private sale.
The most common way to finance a used Toyota Corolla. The car is security for the loan, which usually means a lower rate than an unsecured loan.
See if it suits me
No security over the car, so older or cheaper cars can qualify. Rates are usually higher than a secured car loan.
See if it suits me
Get a lender’s conditional OK before you shop, so you know your budget and can move fast on the right Corolla.
See if it suits me
Other used Toyotas worth a look: the Toyota Hilux, Toyota RAV4 and Toyota LandCruiser.
Before you talk to a seller, run the numbers through the car loan calculator to see how the loan amount, term and your credit history change the repayment. Then read how UsedCarLoans works so you know what happens after you send your details.
Most buyers ask the same things about deposits, credit checks and loan terms, so we answered them in our used car finance FAQs. Ready to go? Start the quick quiz and a licensed broker can talk you through what lenders may offer.
Answer a few questions and a broker checks what lenders may offer, so you know your budget before you shop.
Shop dealers, Marketplace and private listings within your budget. Compare a few similar cars on age, kilometres and price.
Run a PPSR search, book an independent inspection and go through the service history before you commit.
Send the car’s details to your broker. The lender confirms its value and that it’s free of existing finance.
Sign your loan documents, the lender pays the seller, and the Corolla is yours.
Lenders may finance a used Corolla from either. Here’s how they compare.
 On the yard
 In a driveway
Your loan covers the car. Running a used Toyota Corolla also means:
Yes, a used Corolla is one of the safest bets in the small car market. It has a long record of reliability, parts are cheap and easy to find, and almost every mechanic in Australia knows how to work on one. The trade-off is that demand keeps used prices firm, so you may pay a little more than for a similar Kia Cerato or Hyundai i30 of the same age.
The current generation, sold here from 2018, is the pick if your budget stretches: it has a stronger safety package, a smoother drive and the option of a hybrid. The 2013 to 2018 hatch is a solid middle ground with plenty of choice. Older cars from the late 2000s are still dependable runabouts, but check that safety features like stability control and enough airbags are fitted.
Corollas have few serious faults, so focus on condition and history. Some early 2000s 1.8 litre engines are known to use oil, so check the level and look for blue smoke. On CVT automatics from about 2013, the transmission should feel smooth with no shudder or whine. Also check for kerb-scraped bumpers, worn suspension bushes and air conditioning that blows properly cold.
A well-serviced Corolla can comfortably pass 250,000 km, so mileage matters less than maintenance. A car on 180,000 km with a full logbook is often a better buy than one on 90,000 km with gaps in its history. Expect to replace wear items such as the water pump, shocks and clutch on manual cars somewhere past the 150,000 km mark, and factor that into your offer.
Choose the hybrid if you do lots of stop-start city driving, where it uses noticeably less fuel. The petrol suits highway commuters and buyers who want to spend less up front, since hybrids usually cost more second-hand. Both are reliable. On a hybrid, ask whether the annual hybrid battery health check has been done at a Toyota dealer, as that can affect the battery cover still available.
It depends what you value. The Corolla usually wins on reliability reputation and resale value. A Mazda3 tends to feel more upmarket inside and is often sharper to drive, while an i30 of the same age can cost less to buy and may come with more features for the money. All three are sensible used buys, so let condition and service history decide between two similar cars.
Corolla servicing is very affordable by Australian standards. Newer models are covered by Toyota capped price servicing for a set period, usually at 12 month or 15,000 km intervals, and you can check the prices for a specific car on Toyota's website. Older Corollas out of that program can be serviced at any independent mechanic, and basic parts like filters and brake pads are inexpensive.
Most owners never need one, because Toyota hybrid batteries commonly last well beyond 200,000 km. If a replacement is needed, the price depends on the generation and whether you choose a new genuine pack or a reconditioned one, so get a quote from a Toyota dealer and a hybrid specialist. On newer cars, Toyota offers extended battery cover when the annual health check is kept up.
Yes, the Corolla is one of the strongest small cars for resale in Australia. Steady demand from first-car buyers, families and rideshare drivers means it loses value more slowly than many rivals. That helps if you finance one, because the car is less likely to be worth far less than you owe partway through the loan. It also means bargains are rare, so be patient.
Pick the hatch if you want easier parking and a flexible boot that takes bulky items with the seats folded. The sedan has more rear legroom and a bigger, more secure boot, which suits small families and people who carry passengers often. In the current generation, sedans are also a little cheaper second-hand in some grades. Mechanically they share most parts, so reliability is the same.
Yes, it is one of the most popular choices for new drivers. Corollas are easy to drive, cheap to fix and usually sit in lower insurance brackets than sporty hatches, which matters because young drivers pay more for cover. Choose a newer model if you can, as later generations have more airbags, autonomous emergency braking and better crash ratings. Check P plate power limits in your state.
Most Corollas from around 2020 onwards have Apple CarPlay and Android Auto, though it depends on the build date and grade, so check the specific car. Earlier models from the current generation may need a software update from a Toyota dealer. Older Corollas generally do not have it, but an aftermarket head unit can usually be fitted for a reasonable price by an auto electrician.
Often, yes. Many lenders will finance an older Corolla because it holds value and is cheap to repair, but most set a maximum car age at the end of the loan. That means a 10 year old car may only qualify for a shorter term, which lifts the repayments. If the car is very old or cheap, a broker may suggest an unsecured personal loan instead.
Borrow only what you need for a car that suits you, plus a small buffer for rego, insurance and a first service. Corollas cover a wide price range, from older runabouts to near-new hybrids, so decide on a generation and grade first. A smaller loan over a shorter term usually costs less in total interest. Try a repayment calculator before you start looking.
It can be possible. Lenders mostly want to see stable income, savings habits and that the repayments fit your budget. A thin credit file is not the same as a bad one, though some lenders may ask for a deposit or a shorter term. A sensibly priced Corolla is the kind of low-risk first car many lenders may consider for younger borrowers.
It can be, but check it closely. Corollas are popular with rental fleets and rideshare drivers, so many have high kilometres for their age and heavy rear seat and interior wear. Fleet cars are usually serviced on time, which helps. Lenders generally finance them like any other used car, but a high-mileage example may be valued lower, which affects how much you can borrow against it.
Possibly. Some lenders offer green or low-emissions car loans, and a hybrid Corolla may meet their criteria, though many set rules on the vehicle's emissions rating, age or whether it is new. Pricing and conditions differ between lenders, and a green loan is not always the best overall deal. A broker can compare green and standard options side by side for the car you choose.
A PPSR search shows whether money is still owed on the car, whether it has been reported stolen and whether it was written off. It costs a few dollars on the official PPSR website and only needs the VIN. Run it on every private sale Corolla. If finance is still owed and not paid out, the lender can repossess the car even after you buy it.
Yes, many lenders will fund a private sale. They usually need the seller's details, the VIN and rego, and proof the seller owns the car. Some lenders pay the seller directly, and may also pay out any existing finance so the car changes hands clear. Getting pre-approval first lets you negotiate on a private Corolla knowing exactly what you can spend.